Most phone append services look the same on the surface.
They promise “premium data,” high match rates, fast turnaround, and compliance. For a company processing a few thousand records a month, that may be enough. For major banks, mortgage lenders, and debt settlement firms running high-volume operations, it usually isn’t.
For large companies, phone append is about more than filling in missing phone numbers. They need accurate matches, up-to-date contact details, and reliable results across large volumes of records. They also need pricing that fits their budget and a turnaround time they can count on. Having accurate phone data helps sales and marketing teams work with better contact lists and spend less time dealing with missing or outdated information. When a company processes hundreds of thousands of records, these details matter even more.
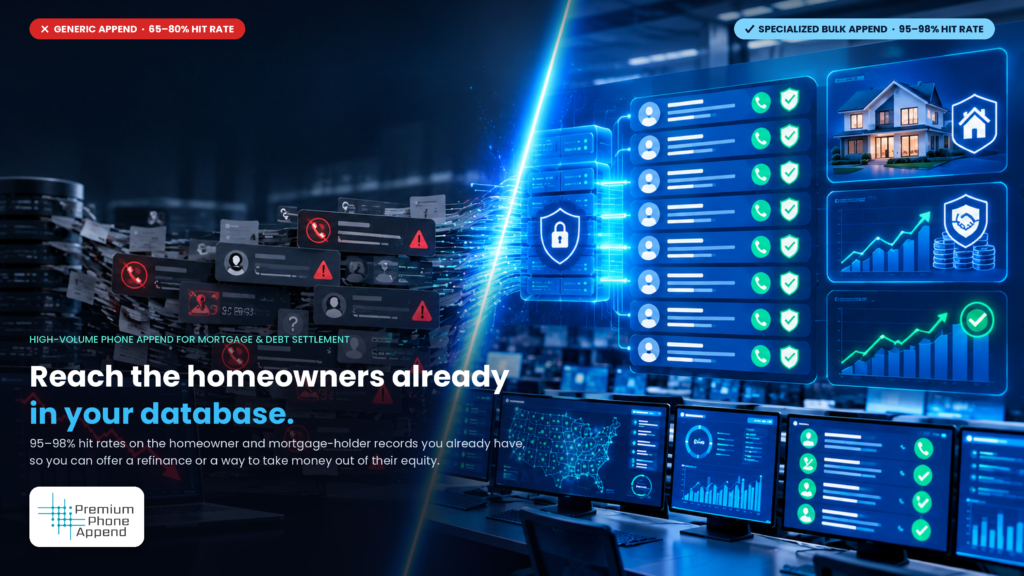
When you’re updating tens or hundreds of thousands of existing homeowner records every month, the difference between a 70% hit rate and a 95–98% hit rate isn’t a minor improvement. It’s the difference between leaving a large share of your database unreachable and actually reaching the homeowners already in your database.
The High-Volume Problem Generic Append Services Don’t Solve
Major mortgage companies already hold large databases of homeowners, most of whom already have a mortgage. When rates drop or home values rise, those homeowners become strong candidates to refinance or to take money out of their equity. That opportunity only pays off if the lender can actually reach them, and the phone numbers on file often went stale long ago.
Major mortgage companies and debt settlement firms don’t just need phone numbers. They need:
- High hit rates on the homeowner records they already have
- Consistent quality at bulk scale
- Numbers that are actually dialable (with accurate line-type identification)
- Speed that supports time-sensitive refinance and outreach campaigns
- Compliance handling that holds up under volume
Most append providers optimize for the general market. They take whatever list you send them and match it against a broad database. That works reasonably well for mixed or low-value data. It breaks down on the records lenders care about most: existing homeowner files where contact details have gone out of date as people change numbers, drop landlines, or switch carriers.
The result is familiar: contact rates that look good on paper but collapse once the dialer starts. Loan officers and agents waste time on bad numbers. Cost per funded loan or enrolled debt case stays higher than it should be. Aged records that could have been reactivated for a refinance or equity offer sit unused.
What Changes with a Specialized Bulk Append Engine
A small number of companies have built their entire model around high-volume mortgage and debt data rather than trying to serve every industry equally.
The difference shows up in a few specific places:
Hit rates on existing homeowner data. The strongest specialized providers consistently deliver 95–98% hit rates on existing homeowner and mortgage-holder records. That’s not a marketing claim pulled from an old database test—it’s the result of matching against multiple top-tier sources (including the credit bureaus) through a proprietary API. At that level, the gap versus typical 65–80% append services becomes very visible in contact rates and cost per acquisition.
Volume readiness. Enterprise lenders don’t want a vendor that handles 10,000 records well and struggles at 250,000+. They need a supplier that already operates at bulk scale and can return updated, ready-to-work records without a long setup or custom project every time.
Quality of the underlying data. The best results come from records that already carry strong signals: homeowners who already hold a mortgage, with names, addresses, and property details already on file. The append step turns those records into dial-ready contacts, so loan officers can reach homeowners about a refinance or about taking money out of their equity. Because the file is data the lender already has, the usual suppressions can be applied before or after the append, keeping outreach aligned with existing compliance rules. In practice, the resulting lists rank among the strongest available in mortgage and debt settlement because of the combination of homeowner data already on file and append quality.
Transparency. Companies that live in this space are usually straightforward about how the data is built. That clarity helps compliance teams and operations leaders evaluate the product properly instead of discovering limitations later.
What This Looks Like in Practice
Lenders and debt firms that move to a specialized high-volume append partner typically report:
- Higher contact rates (often moving from the low-to-mid 20% range into the 60–70%+ range on previously hard-to-reach homeowners)
- Lower cost per funded loan or enrolled case because fewer records are wasted
- Faster outreach when rate drops or rising home values open refinance and equity opportunities
- Better reactivation of aged inventory that already has names and addresses
- Cleaner integration with AI dialers, SMS, and CRM systems because line type and confidence data come with the numbers
The companies seeing the biggest gains are usually the ones already sitting on large homeowner databases and simply needed a better way to turn those records into live conversations.
The Bottom Line for Enterprise Buyers
If your operation is high-volume and specialized in mortgage or debt settlement, a generic phone append service is often the expensive choice—even when the price per match looks low. The real cost shows up in missed contacts, lower conversion, and higher cost per outcome.
Specialized bulk providers that can consistently deliver 95–98% hit rates on existing homeowner data, draw from top-tier sources including the bureaus, and already serve major banks and mortgage companies give you a different set of economics. You’re not just buying phone numbers. You’re buying a higher percentage of usable, dial-ready contacts on the exact records you already know how to convert.
That gap is why more high-volume mortgage lenders and debt settlement firms are moving away from interchangeable append vendors and toward partners built specifically for the volume and data quality their business requires.
If you’re evaluating append quality at scale, the fastest way to see the difference is a controlled test on a sample of your own homeowner file. The numbers usually speak for themselves.